
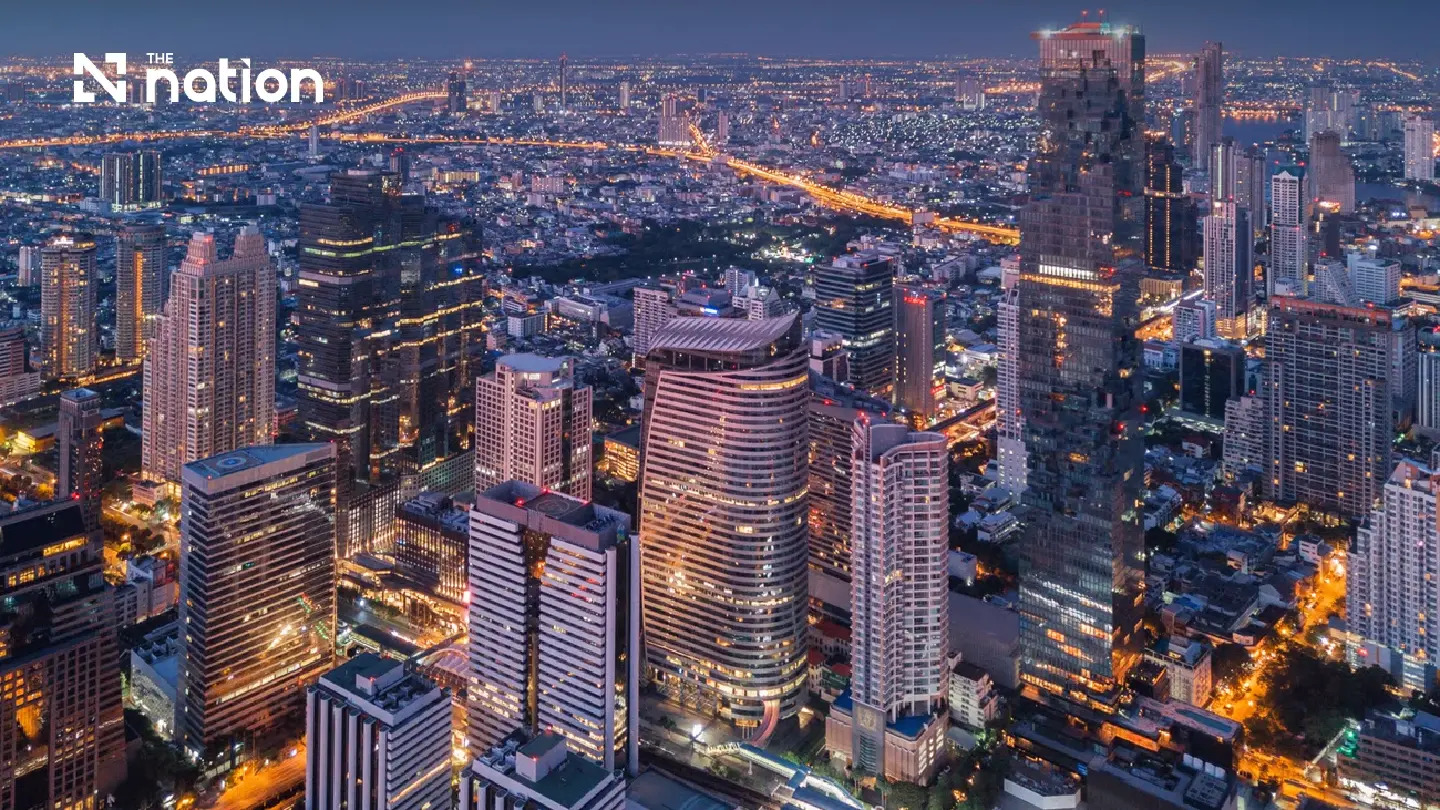
 Bangkok ultra-luxury condos could top 1 million baht per square metre
THIS NEWS ARTICLE KINDLY SPONSORED BY FALLPROTEC, A WORLD-RENOWNED NAME IN THE DESIGN AND MANUFACTURE OF PREMIUM FALL PROTECTION SYSTEMS AND HEIGHT ACCESS SOLUTIONS
- Property consultancy Savills predicts that ultra-luxury condominium prices in prime Bangkok locations could soon exceed 1 million baht per square metre, driven by rising land costs and high demand from wealthy buyers.
- This trend is fueled by the expansion of branded residences, where developers partner with international brands to offer premium services and exclusivity, commanding higher prices.
- Soaring land costs are a major factor, exemplified by a recent land sale for a luxury project that reached over 875,000 baht per square metre, pushing up final development prices.
- Strong market demand for such properties is already evident, with the Upper House branded residences achieving sales of over 10 billion baht, including units priced above 850,000 baht per square metre.
Bangkok’s ultra-luxury condominium prices could exceed 1 million baht per square metre in the near future, according to Savills, as rising prime land costs, distinctive developments and demand from wealthy buyers support the top end of the market.
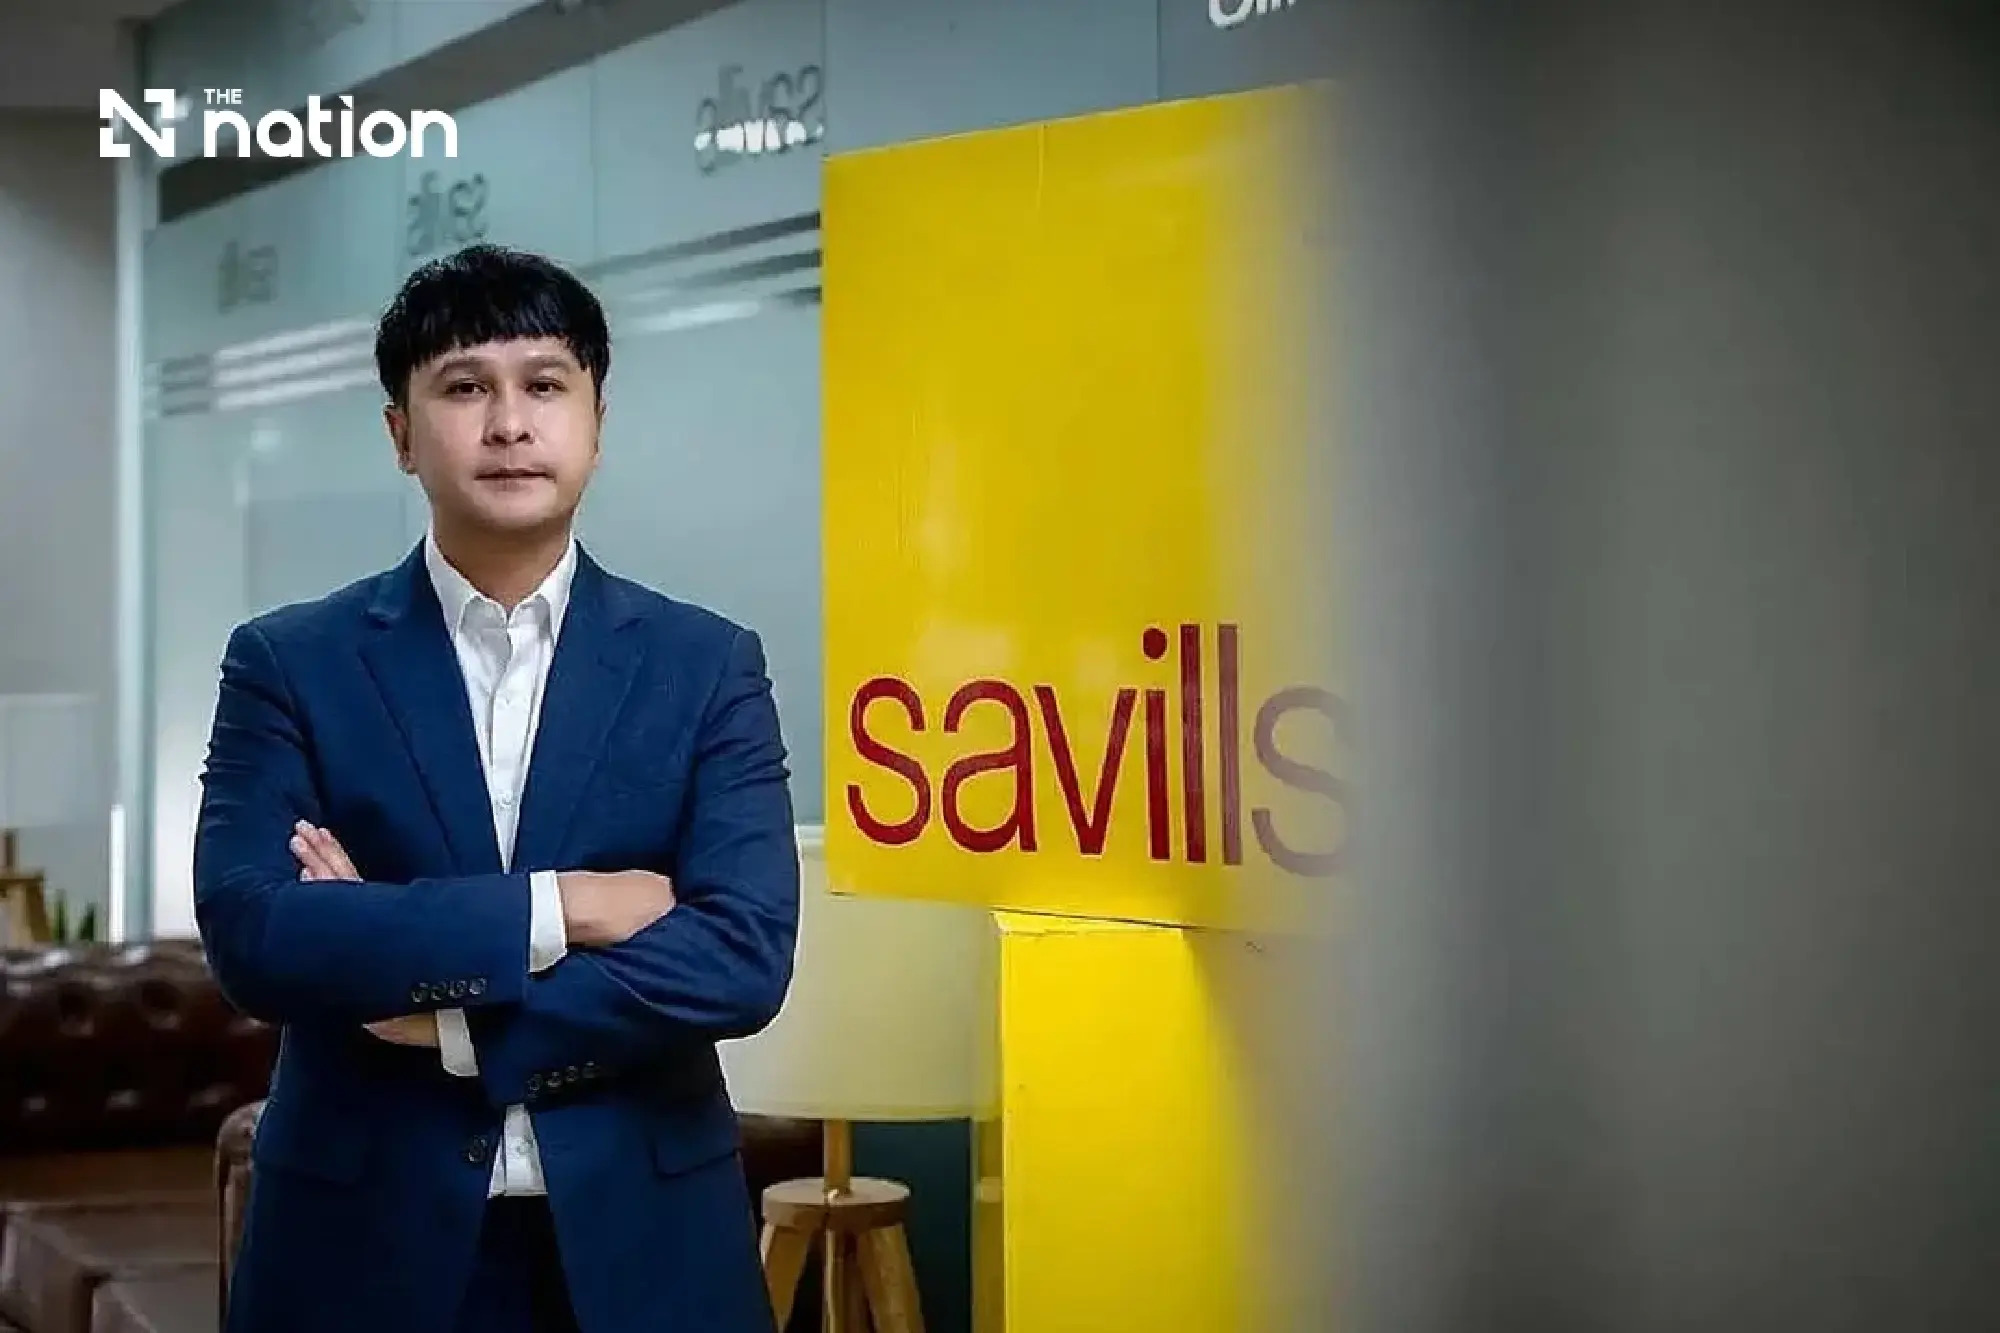
Phattarachai Taweewong, senior director of market research and public relations at Savills (Thailand), puts the potential price shift in the Ultimate Class segment in high-potential locations, rather than the broader condominium market.
The forecast comes as Thailand’s branded-residences sector, comprising homes associated with international brands and their service standards, expands into a market worth around 220 billion baht.
Prime locations drive development costs
Lumphini, Langsuan and Sarasin are attracting new launches and the renewed marketing of existing developments. Access to business and lifestyle districts, scarce land and a limited choice of luxury projects are increasing development costs and sharpening competition.
Activity includes the relaunch of NIMIT Lumpini Park North, CG Capital’s luxury developments in Langsuan, Capella Residences and Sansiri’s luxury condominium project in the Sarasin area.
Developers increasingly need to offer more than an address and facilities. Affluent buyers are placing greater value on privacy, brand reputation, service quality and distinctive living experiences, alongside the prestige of ownership.
International brands are becoming involved in everything from design concepts to service standards and relationships with residents, helping developers distinguish their projects.
Upper House sales highlight premium demand
Upper House branded residences in Bangkok, the brand’s first residential development worldwide, recorded sales exceeding 10 billion baht within six months of launch. Some units were priced above 850,000 baht per square metre.
The performance illustrates demand for developments combining an established brand, a prime location and high residential standards.
InterContinental Residences Bangkok Asoke, developed by CG Capital with IHG Hotels & Resorts and launched in late 2025, has also attracted sustained interest, with reports of strong sales.
Such developments reflect a market increasingly focused on the experience of living in a property, rather than its location and facilities alone.
Rosewood illustrates the pressure from land prices
Rosewood Residences Bangkok, developed by SC Asset with Tokyo Tatemono Group, is the brand’s first residential project in Southeast Asia. Rosewood describes the development as 85 private residences spread across 37 floors, with an emphasis on privacy and exclusivity.
The project occupies the former Sri Fuang Foon Building site on Rama IV Road. The 0.3948-hectare plot was reportedly sold in 2024 for more than 3.5 million baht per square wah, equivalent to over 875,000 baht per square metre, at a total value exceeding 3.5 billion baht.
Savills estimates that selling prices at the development could exceed 550,000 baht per square metre.
Such land costs increase the pressure to create additional value through architecture, brand credibility, limited unit numbers and hotel-standard services. Whether buyers continue to accept premium prices depends on the value they attach to these features relative to the additional cost.
Thailand’s branded market reaches 18,801 units
Thailand has the largest number of completed branded residential projects in Asia-Pacific and ranks among the world’s top 10 markets by the number of projects under development.
Savills puts cumulative supply at approximately 18,801 units worth around 220 billion baht. It expects about 650 new units to be launched for sale in 2026, up approximately 32% from the previous year, with Bangkok and Phuket remaining the principal growth markets.
However, branded residences are not confined to the highest price tiers.
High-end projects priced at 150,000–249,999 baht per square metre account for the largest share of supply, at around 42%. The Upscale segment, priced at 100,000–149,999 baht per square metre, represents approximately 23%.
These figures show that branding also serves as a way to differentiate properties below the ultra-luxury tier. Developers must match their chosen brand to the selling price, target buyers and intended residential experience.
Regional pipeline points to growth through 2032
A report by Savills Global Residential Development Consultancy puts Asia-Pacific’s share of completed branded residential projects worldwide at approximately 23%.
Another 187 projects are expected to be delivered in the region by 2032, an increase of around 97%. Thailand’s project count is forecast to rise by 152% over the same period.
Future growth depends not only on established markets but also on expansion into new countries and cities, alongside a broader mix of brands and development formats.
Wealth accumulation provides another source of demand. The value of assets held by billionaires worldwide has increased by 121% over the past decade, while high-net-worth and ultra-high-net-worth individuals have become increasingly influential buyers.
Demand from within Asia is broadening the customer base and reducing reliance on purchasers from outside the region.
Phuket attracts holiday-home and investment buyers
Phuket’s international tourism profile supports demand from Thai and foreign holiday-home buyers, while interest is also extending to Chonburi and Hua Hin.
Beachfront locations, resort-style living and recognised service standards appeal to purchasers seeking both personal use and long-term ownership.
However, the investment case depends on more than a destination’s popularity. Actual rental demand, management costs, seasonal fluctuations and each project’s terms also need to be considered.
A 31% price premium is not a guaranteed return
Savills estimates that branded residences can command an average selling-price premium of approximately 31% over comparable unbranded luxury properties.
That premium does not guarantee an investment return or success for every development. Location, design quality, brand credibility, purchasing power and market conditions at launch all influence what buyers are prepared to pay.
Likewise, higher asking prices do not necessarily translate into higher prices in completed transactions. The affluent buyer base is limited, making the market’s ability to absorb new supply a critical consideration.
Developments that offer distinctive locations, design and service may sustain premium prices. Those priced above buyers’ perceptions of value could face difficulties completing sales over the longer term.
As competition intensifies for international brands and scarce prime sites, developers face a challenge beyond creating a luxury image: converting brand reputation into actual sales and preserving long-term asset value through services and experiences that residents value.
Source: https://www.nationthailand.com/business/property/40072888 (Krungthep Turakij)
Google Translation:
[We apologise if any of the translation is incorrect: google Translation occasionally gets it wrong]
คอนโดมิเนียมระดับอัลตราลักชัวรีในกรุงเทพฯ อาจมีราคาพุ่งสูงเกิน 1 ล้านบาทต่อตารางเมตร
บทความข่าวนี้ได้รับการสนับสนุนโดย FALLPROTEC แบรนด์ระดับโลกที่มีชื่อเสียงด้านการออกแบบและผลิตระบบป้องกันการตกจากที่สูงและโซลูชันสำหรับการเข้าถึงพื้นที่สูงระดับพรีเมียม
Savills บริษัทที่ปรึกษาด้านอสังหาริมทรัพย์ คาดการณ์ว่าราคาคอนโดมิเนียมระดับอัลตราลักชัวรีในทำเลทองของกรุงเทพฯ อาจพุ่งสูงเกิน 1 ล้านบาทต่อตารางเมตรในเร็วๆ นี้ โดยได้รับแรงหนุนจากราคาที่ดินที่ปรับตัวสูงขึ้นและความต้องการที่แข็งแกร่งจากกลุ่มผู้ซื้อที่มีฐานะมั่งคั่ง
แนวโน้มดังกล่าวได้รับแรงส่งจากการขยายตัวของโครงการที่อยู่อาศัยภายใต้แบรนด์ระดับโลก (Branded Residences) ซึ่งผู้พัฒนาโครงการได้ร่วมมือกับแบรนด์ต่างประเทศเพื่อมอบบริการระดับพรีเมียมและความเป็นเอกสิทธิ์เฉพาะตัว ส่งผลให้สามารถตั้งราคาขายได้สูงขึ้น
ราคาที่ดินที่พุ่งสูงขึ้นถือเป็นปัจจัยสำคัญ โดยเห็นได้จากการซื้อขายที่ดินสำหรับโครงการหรูแห่งหนึ่งเมื่อเร็วๆ นี้ ซึ่งมีราคามากกว่า 875,000 บาทต่อตารางเมตร ส่งผลให้ราคาขายสุดท้ายของโครงการสูงขึ้นตามไปด้วย
ความต้องการในตลาดสำหรับอสังหาริมทรัพย์ประเภทนี้มีความชัดเจนอยู่แล้ว โดยโครงการที่อยู่อาศัยภายใต้แบรนด์ระดับโลกอย่าง “Upper House” มียอดขายรวมกว่า 1 หมื่นล้านบาท ซึ่งรวมถึงยูนิตที่มีราคาขายสูงกว่า 850,000 บาทต่อตารางเมตร
Savills ระบุว่า ราคาคอนโดมิเนียมระดับอัลตราลักชัวรีในกรุงเทพฯ อาจทะลุ 1 ล้านบาทต่อตารางเมตรในอนาคตอันใกล้ เนื่องจากราคาที่ดินในทำเลศักยภาพสูงที่ปรับตัวเพิ่มขึ้น ประกอบกับการพัฒนาโครงการที่มีความโดดเด่นและความต้องการจากกลุ่มผู้ซื้อที่มีกำลังซื้อสูง ซึ่งเป็นปัจจัยสนับสนุนตลาดระดับบนสุดนี้
ภัทรชัย ทวีวงศ์ ผู้อำนวยการอาวุโสฝ่ายวิจัยตลาดและสื่อสารองค์กรของ Savills (ประเทศไทย) กล่าวว่า การปรับตัวของราคาในระดับนี้จะเกิดขึ้นเฉพาะในกลุ่ม “Ultimate Class” (ระดับสูงสุด) ในทำเลที่มีศักยภาพสูงเท่านั้น ไม่ใช่ภาพรวมของตลาดคอนโดมิเนียมทั้งหมด
การคาดการณ์ดังกล่าวเกิดขึ้นในขณะที่ตลาดที่อยู่อาศัยภายใต้แบรนด์ระดับโลก (Branded Residences) ในประเทศไทย ซึ่งเป็นโครงการที่อยู่อาศัยที่เชื่อมโยงกับแบรนด์ต่างประเทศและมาตรฐานการบริการของแบรนด์เหล่านั้น กำลังขยายตัวจนมีมูลค่าตลาดรวมประมาณ 2.2 แสนล้านบาท
ทำเลทองผลักดันต้นทุนการพัฒนาโครงการ
ย่านลุมพินี หลังสวน และสารสิน กำลังได้รับความสนใจทั้งจากการเปิดตัวโครงการใหม่และการกลับมาทำตลาดโครงการที่มีอยู่เดิม ด้วยทำเลที่ตั้งซึ่งเข้าถึงย่านธุรกิจและไลฟ์สไตล์ได้สะดวก ประกอบกับที่ดินที่มีอยู่อย่างจำกัดและโครงการระดับหรูที่มีให้เลือกไม่มากนัก จึงส่งผลให้ต้นทุนการพัฒนาโครงการสูงขึ้นและการแข่งขันมีความเข้มข้นยิ่งขึ้น
ความเคลื่อนไหวในตลาดนี้รวมถึงการกลับมาทำตลาดอีกครั้งของโครงการ NIMIT Lumpini Park North, โครงการระดับหรูในย่านหลังสวนโดย CG Capital, โครงการ Capella Residences รวมถึงโครงการคอนโดมิเนียมระดับหรูของแสนสิริในย่านสารสิน ปัจจุบัน ผู้พัฒนาอสังหาริมทรัพย์จำเป็นต้องนำเสนอสิ่งที่มากกว่าแค่ทำเลที่ตั้งและสิ่งอำนวยความสะดวก โดยกลุ่มผู้ซื้อที่มีกำลังซื้อสูงให้ความสำคัญมากขึ้นกับความเป็นส่วนตัว ชื่อเสียงของแบรนด์ คุณภาพการบริการ และประสบการณ์การอยู่อาศัยที่โดดเด่น ควบคู่ไปกับความภาคภูมิใจในการเป็นเจ้าของ
แบรนด์ระดับสากลเข้ามามีบทบาทในทุกขั้นตอน ตั้งแต่แนวคิดการออกแบบไปจนถึงมาตรฐานการบริการและการสร้างความสัมพันธ์กับผู้อยู่อาศัย ซึ่งช่วยให้ผู้พัฒนาสามารถสร้างความแตกต่างให้กับโครงการของตนได้
ยอดขายโครงการ Upper House สะท้อนความต้องการในตลาดระดับพรีเมียม
โครงการที่อยู่อาศัยภายใต้แบรนด์ Upper House ในกรุงเทพฯ ซึ่งถือเป็นโครงการที่อยู่อาศัยแห่งแรกของแบรนด์นี้ในระดับโลก มียอดขายรวมกว่า 1 หมื่นล้านบาทภายในระยะเวลาเพียง 6 เดือนหลังเปิดตัว โดยบางยูนิตมีราคาขายสูงกว่า 850,000 บาทต่อตารางเมตร
ความสำเร็จดังกล่าวสะท้อนให้เห็นถึงความต้องการโครงการที่ผสมผสานระหว่างแบรนด์ที่มีชื่อเสียง ทำเลที่ตั้งชั้นเยี่ยม และมาตรฐานการอยู่อาศัยระดับสูง
นอกจากนี้ โครงการ InterContinental Residences Bangkok Asoke ซึ่งพัฒนาโดย CG Capital ร่วมกับ IHG Hotels & Resorts และเปิดตัวในช่วงปลายปี 2025 ก็ได้รับความสนใจอย่างต่อเนื่อง โดยมีรายงานว่ามียอดขายที่แข็งแกร่งเช่นกัน
โครงการในลักษณะนี้สะท้อนให้เห็นว่าตลาดกำลังให้ความสำคัญกับ “ประสบการณ์การอยู่อาศัย” มากขึ้น แทนที่จะพิจารณาเพียงแค่ทำเลที่ตั้งและสิ่งอำนวยความสะดวกเท่านั้น
กรณีของ Rosewood สะท้อนแรงกดดันจากราคาที่ดิน
โครงการ Rosewood Residences Bangkok ซึ่งพัฒนาโดย SC Asset ร่วมกับ Tokyo Tatemono Group ถือเป็นโครงการที่อยู่อาศัยแห่งแรกของแบรนด์นี้ในเอเชียตะวันออกเฉียงใต้ โดยประกอบด้วยที่อยู่อาศัยส่วนตัวจำนวน 85 ยูนิต กระจายอยู่บนพื้นที่ 37 ชั้น ซึ่งเน้นความเป็นส่วนตัวและความพิเศษเฉพาะตัวเป็นสำคัญ
โครงการนี้ตั้งอยู่บนพื้นที่เดิมของอาคารศรีเฟื่องฟูน (Sri Fuang Foon Building) บนถนนพระราม 4 โดยที่ดินขนาดประมาณ 0.3948 เฮกตาร์ (หรือประมาณ 2 ไร่ 1 งาน 79 ตารางวา) แห่งนี้ มีรายงานว่าถูกขายไปในปี 2024 ในราคามากกว่า 3.5 ล้านบาทต่อตารางวา หรือคิดเป็นมูลค่ากว่า 875,000 บาทต่อตารางเมตร รวมมูลค่าที่ดินทั้งสิ้นกว่า 3.5 พันล้านบาท
ภัทรชัย ทวีวงศ์ ผู้อำนวยการอาวุโสฝ่ายวิจัยตลาดและสื่อสารองค์กรของบริษัท Savills (ประเทศไทย)
Savills คาดการณ์ว่าราคาขายของโครงการนี้อาจสูงกว่า 550,000 บาทต่อตารางเมตร ต้นทุนที่ดินที่สูงขึ้นเช่นนี้ ผลักดันให้ผู้พัฒนาโครงการต้องสร้างมูลค่าเพิ่มผ่านงานสถาปัตยกรรม ความน่าเชื่อถือของแบรนด์ การจำกัดจำนวนยูนิต และการให้บริการในระดับโรงแรม ทั้งนี้ การที่ผู้ซื้อจะยังคงยอมรับราคาในระดับพรีเมียมได้หรือไม่นั้น ขึ้นอยู่กับว่าผู้ซื้อให้คุณค่ากับองค์ประกอบเหล่านี้มากน้อยเพียงใดเมื่อเทียบกับต้นทุนส่วนเพิ่มที่ต้องจ่ายไป
ตลาดที่อยู่อาศัยภายใต้แบรนด์ (Branded Residences) ในประเทศไทยมีจำนวนรวมทั้งสิ้น 18,801 ยูนิต
ประเทศไทยมีจำนวนโครงการที่อยู่อาศัยภายใต้แบรนด์ที่สร้างเสร็จแล้วมากที่สุดในภูมิภาคเอเชียแปซิฟิก และยังติดอันดับ 1 ใน 10 ตลาดที่มีโครงการอยู่ระหว่างการพัฒนามากที่สุดในโลกอีกด้วย
Savills ระบุว่ามีอุปทานสะสมรวมทั้งสิ้นประมาณ 18,801 ยูนิต คิดเป็นมูลค่าราว 220 พันล้านบาท โดยคาดการณ์ว่าจะมีโครงการใหม่เปิดตัวอีกประมาณ 650 ยูนิตในปี 2026 ซึ่งเพิ่มขึ้นจากปีก่อนหน้าประมาณ 32% โดยกรุงเทพฯ และภูเก็ตยังคงเป็นตลาดหลักที่มีการเติบโต
อย่างไรก็ตาม โครงการที่อยู่อาศัยภายใต้แบรนด์ (Branded Residences) ไม่ได้จำกัดอยู่เพียงกลุ่มที่มีราคาสูงที่สุดเท่านั้น
โครงการระดับไฮเอนด์ (High-end) ซึ่งมีราคาขายอยู่ที่ 150,000–249,999 บาทต่อตารางเมตร ถือเป็นสัดส่วนที่ใหญ่ที่สุดของอุปทานทั้งหมด โดยคิดเป็นประมาณ 42% ในขณะที่กลุ่มอัปสเกล (Upscale) ซึ่งมีราคาอยู่ที่ 100,000–149,999 บาทต่อตารางเมตร มีสัดส่วนอยู่ที่ประมาณ 23%
ตัวเลขเหล่านี้แสดงให้เห็นว่า การใช้แบรนด์ยังเป็นกลยุทธ์ในการสร้างความแตกต่างให้กับอสังหาริมทรัพย์ที่อยู่นอกเหนือไปจากกลุ่มอัลตราลักชัวรี (Ultra-luxury) ได้อีกด้วย ผู้พัฒนาโครงการจำเป็นต้องเลือกแบรนด์ให้สอดคล้องกับราคาขาย กลุ่มเป้าหมาย และประสบการณ์การอยู่อาศัยที่ต้องการนำเสนอ
โครงการในอนาคตทั่วภูมิภาคชี้ให้เห็นถึงการเติบโตต่อเนื่องจนถึงปี 2032
รายงานจาก Savills Global Residential Development Consultancy ระบุว่า ภูมิภาคเอเชียแปซิฟิกมีสัดส่วนโครงการที่อยู่อาศัยภายใต้แบรนด์ที่สร้างเสร็จแล้วประมาณ 23% ของจำนวนโครงการทั้งหมดทั่วโลก
คาดว่าจะมีโครงการอีก 187 แห่งในภูมิภาคนี้ที่จะแล้วเสร็จภายในปี 2032 ซึ่งเป็นการเพิ่มขึ้นถึงประมาณ 97% โดยในส่วนของประเทศไทย คาดการณ์ว่าจำนวนโครงการจะเพิ่มขึ้นถึง 152% ในช่วงเวลาเดียวกัน
การเติบโตในอนาคตไม่ได้ขึ้นอยู่กับตลาดเดิมที่มีอยู่แล้วเท่านั้น แต่ยังรวมถึงการขยายตัวไปยังประเทศและเมืองใหม่ๆ ควบคู่ไปกับการเพิ่มความหลากหลายของแบรนด์และรูปแบบการพัฒนาโครงการ
การสะสมความมั่งคั่งเป็นอีกหนึ่งปัจจัยที่ขับเคลื่อนความต้องการ โดยมูลค่าทรัพย์สินที่ถือครองโดยมหาเศรษฐีระดับพันล้านดอลลาร์ทั่วโลกได้เพิ่มขึ้นถึง 121% ในช่วงทศวรรษที่ผ่านมา ในขณะที่กลุ่มบุคคลที่มีความมั่งคั่งสูง (High-net-worth individuals) และกลุ่มที่มีความมั่งคั่งสูงมาก (Ultra-high-net-worth individuals) ได้กลายเป็นกลุ่มผู้ซื้อที่มีอิทธิพลมากขึ้นเรื่อยๆ
ความต้องการจากภายในภูมิภาคเอเชียเองกำลังช่วยขยายฐานลูกค้าให้กว้างขึ้น และลดการพึ่งพาผู้ซื้อจากนอกภูมิภาค
ภูเก็ตดึงดูดทั้งผู้ซื้อบ้านพักตากอากาศและนักลงทุน
ชื่อเสียงด้านการท่องเที่ยวระดับนานาชาติของภูเก็ตช่วยสนับสนุนความต้องการจากทั้งผู้ซื้อชาวไทยและชาวต่างชาติที่มองหาบ้านพักตากอากาศ นอกจากนี้ ความสนใจดังกล่าวยังขยายตัวไปยังพื้นที่อื่นๆ เช่น ชลบุรี และหัวหินอีกด้วย ทำเลที่ตั้งติดชายหาด การใช้ชีวิตในรูปแบบรีสอร์ต และมาตรฐานการบริการที่เป็นที่ยอมรับ ดึงดูดผู้ซื้อที่ต้องการทั้งเพื่อการอยู่อาศัยส่วนตัวและการถือครองในระยะยาว
อย่างไรก็ตาม ความคุ้มค่าในการลงทุนไม่ได้ขึ้นอยู่กับความนิยมของสถานที่ตั้งเพียงอย่างเดียว แต่ยังต้องพิจารณาถึงความต้องการเช่าที่แท้จริง ค่าใช้จ่ายในการบริหารจัดการ ความผันผวนตามฤดูกาล รวมถึงเงื่อนไขเฉพาะของแต่ละโครงการด้วย
ราคาที่สูงกว่าปกติถึง 31% ไม่ใช่หลักประกันของผลตอบแทนจากการลงทุน
Savills ประเมินว่า โครงการที่อยู่อาศัยภายใต้แบรนด์ชั้นนำ (Branded Residences) สามารถตั้งราคาขายได้สูงกว่าอสังหาริมทรัพย์ระดับลักชัวรีทั่วไปที่ไม่มีแบรนด์กำกับอยู่ประมาณ 31%
ส่วนต่างของราคาที่เพิ่มขึ้นนี้ไม่ได้เป็นเครื่องรับประกันผลตอบแทนจากการลงทุนหรือความสำเร็จของโครงการเสมอไป ปัจจัยต่าง ๆ เช่น ทำเลที่ตั้ง คุณภาพการออกแบบ ความน่าเชื่อถือของแบรนด์ กำลังซื้อของผู้บริโภค และสภาวะตลาดในช่วงเวลาที่เปิดตัว ล้วนมีผลต่อราคาที่ผู้ซื้อเต็มใจจะจ่าย
ในทำนองเดียวกัน ราคาเสนอขายที่สูงกว่าไม่ได้หมายความว่าราคาซื้อขายจริงจะสูงตามไปด้วย เนื่องจากกลุ่มผู้ซื้อที่มีกำลังทรัพย์สูงนั้นมีจำนวนจำกัด ความสามารถของตลาดในการดูดซับอุปทานใหม่จึงเป็นประเด็นสำคัญที่ต้องคำนึงถึง
โครงการที่มีความโดดเด่นทั้งในด้านทำเลที่ตั้ง การออกแบบ และการบริการ อาจสามารถรักษาไว้ซึ่งระดับราคาที่สูงกว่าปกติได้ ในขณะที่โครงการซึ่งตั้งราคาไว้สูงเกินกว่ามูลค่าที่ผู้ซื้อรับรู้ อาจประสบปัญหาในการปิดการขายในระยะยาว
ท่ามกลางการแข่งขันที่ทวีความรุนแรงขึ้นทั้งในการแย่งชิงแบรนด์ระดับสากลและที่ดินทำเลทองที่มีอยู่อย่างจำกัด ผู้พัฒนาโครงการต่างเผชิญกับความท้าทายที่มากกว่าแค่การสร้างภาพลักษณ์ให้ดูหรูหรา นั่นคือการเปลี่ยนชื่อเสียงของแบรนด์ให้กลายเป็นยอดขายจริง พร้อมทั้งรักษาคุณค่าของสินทรัพย์ในระยะยาว ผ่านการบริการและประสบการณ์ที่ผู้อยู่อาศัยให้คุณค่าอย่างแท้จริง


